Quick answer: An annual return is a statutory company snapshot, not the same filing as a tax return or financial statements.
Important: General educational information only. It is not legal, tax or regulatory advice. Verify jurisdiction-specific requirements with a qualified professional and the competent authority.
This guide addresses annual return hong kong from the perspective of a reader who needs a decision, not just a definition. It sets out four criteria, an example, a simple self-assessment and the sources worth reviewing. The decision framework is editorial guidance; it is not a proprietary benchmark or a substitute for professional judgment.
The essentials: what really matters
Cross-border decisions are sensitive to assumptions that are easy to hide in a headline price: product specifications, shipment handovers, jurisdiction, payment terms and the cost of correcting mistakes. Write the scenario down before comparing offers so that every supplier or provider is assessed on the same basis.
At a glance
- Entity type: Identify the applicable company structure and filing deadline
- Information: Confirm registered office, officers and share information
- Form: Check the current NAR1 requirements with the Companies Registry
- Controls: Build reminders and review details before electronic submission
Corporate filing records should be reconciled against the ownership definitions in ultimate beneficial owner requirements.
The four-part evaluation framework
1. Entity type
Identify the applicable company structure and filing deadline. The first practical action is to request one concrete example relevant to your own situation. Ask who produced it, when it was checked and what would make it invalid. Do not accept a broad assurance where a record, document, calculation or observed process can settle the question more reliably.
For annual return hong kong, define an evidence standard for entity type. A useful record identifies the owner, the supporting source and any open exception. If the information is missing, mark the criterion as unverified rather than assuming success. This distinction helps prevent a polished presentation from being mistaken for a tested outcome.
2. Information
Confirm registered office, officers and share information. The first practical action is to request one concrete example relevant to your own situation. Ask who produced it, when it was checked and what would make it invalid. Do not accept a broad assurance where a record, document, calculation or observed process can settle the question more reliably.
For annual return hong kong, define an evidence standard for information. A useful record identifies the owner, the supporting source and any open exception. If the information is missing, mark the criterion as unverified rather than assuming success. This distinction helps prevent a polished presentation from being mistaken for a tested outcome.
3. Form
Check the current NAR1 requirements with the Companies Registry. The first practical action is to request one concrete example relevant to your own situation. Ask who produced it, when it was checked and what would make it invalid. Do not accept a broad assurance where a record, document, calculation or observed process can settle the question more reliably.
For annual return hong kong, define an evidence standard for form. A useful record identifies the owner, the supporting source and any open exception. If the information is missing, mark the criterion as unverified rather than assuming success. This distinction helps prevent a polished presentation from being mistaken for a tested outcome.
4. Controls
Build reminders and review details before electronic submission. The first practical action is to request one concrete example relevant to your own situation. Ask who produced it, when it was checked and what would make it invalid. Do not accept a broad assurance where a record, document, calculation or observed process can settle the question more reliably.
For annual return hong kong, define an evidence standard for controls. A useful record identifies the owner, the supporting source and any open exception. If the information is missing, mark the criterion as unverified rather than assuming success. This distinction helps prevent a polished presentation from being mistaken for a tested outcome.
Ownership records also matter for KYC and company administration; consult beneficial ownership verification.
For a complementary earlier perspective, read the guide to accounting services in Hong Kong.
One-page comparison table
| Criterion | Evidence to request | Decision signal |
|---|---|---|
| Entity type | Quoted term, original record or contract | Identify the applicable company structure and filing deadline |
| Information | Quoted term, original record or contract | Confirm registered office, officers and share information |
| Form | Quoted term, original record or contract | Check the current NAR1 requirements with the Companies Registry |
| Controls | Quoted term, original record or contract | Build reminders and review details before electronic submission |
Illustrated decision framework

Original Reflection Group diagram. The four stages are a practical editorial framework, not a certification or clinical scoring standard.
Interactive decision helper
Use the tool below to organize your own situation. Its output is illustrative and is deliberately not presented as legal, health or financial advice. A low score means more verification is needed, not that the option is automatically wrong.
Four-point decision scorecard
Check each area only after you have evidence relevant to your situation:
0 of 4 criteria verified
Editorial organization aid only; not a professional certification or risk score.Example: applying the framework
A company updates a director midyear and verifies that the annual return reflects the current particulars.
Create a side-by-side matrix for responsibility, cost, lead time, documentation and dispute handling. Ask what happens when the planned process fails: goods arrive late, a document is rejected, or a quality test fails. The answer often matters more than the most optimistic quotation.
In that example, the next step is to record which of the four criteria has persuasive evidence and which remains uncertain. That creates an actionable follow-up: obtain a missing record, change the scope, negotiate responsibility or seek a specialist assessment. It is more useful than declaring a universally best product or method.
Common mistake — and how to avoid it
Do not copy a fee or deadline from an old blog post without checking the Registry. Treat any proposal or article as a starting hypothesis. Confirm the underlying conditions before transferring its conclusion to a different organization, country, health profile or bottle.
Use an evidence trail that is practical to maintain. Date the information, record the person responsible and preserve original quotations or certificates. Local requirements and commercial practice change; reconfirm material conditions with the relevant authority, carrier or professional before signing.
Next steps: a practical checklist
- Write down the particular decision behind your search for annual return hong kong.
- Check entity type with documented evidence, not an assumption.
- Check information with documented evidence, not an assumption.
- Check form with documented evidence, not an assumption.
- Check controls with documented evidence, not an assumption.
- Compare at least two realistic alternatives using the same evaluation conditions.
- Capture outstanding uncertainties and schedule a review before making an irreversible decision.
Frequently asked questions
What is Form NAR1 in Hong Kong?
NAR1 is the annual return form generally used by local private companies to report specified company particulars to the Companies Registry. Requirements differ for other entity types.
What should be checked before filing an annual return?
Confirm company type, incorporation anniversary, current directors and registered office details. Check the Companies Registry’s live guidance for deadlines and filing fees before submission.
Reliable references and further reading
These primary or specialist sources provide context for checking the relevant concepts. Their existence does not mean they endorse this article or its editorial scoring framework.
- Hong Kong Companies Registry annual return forms
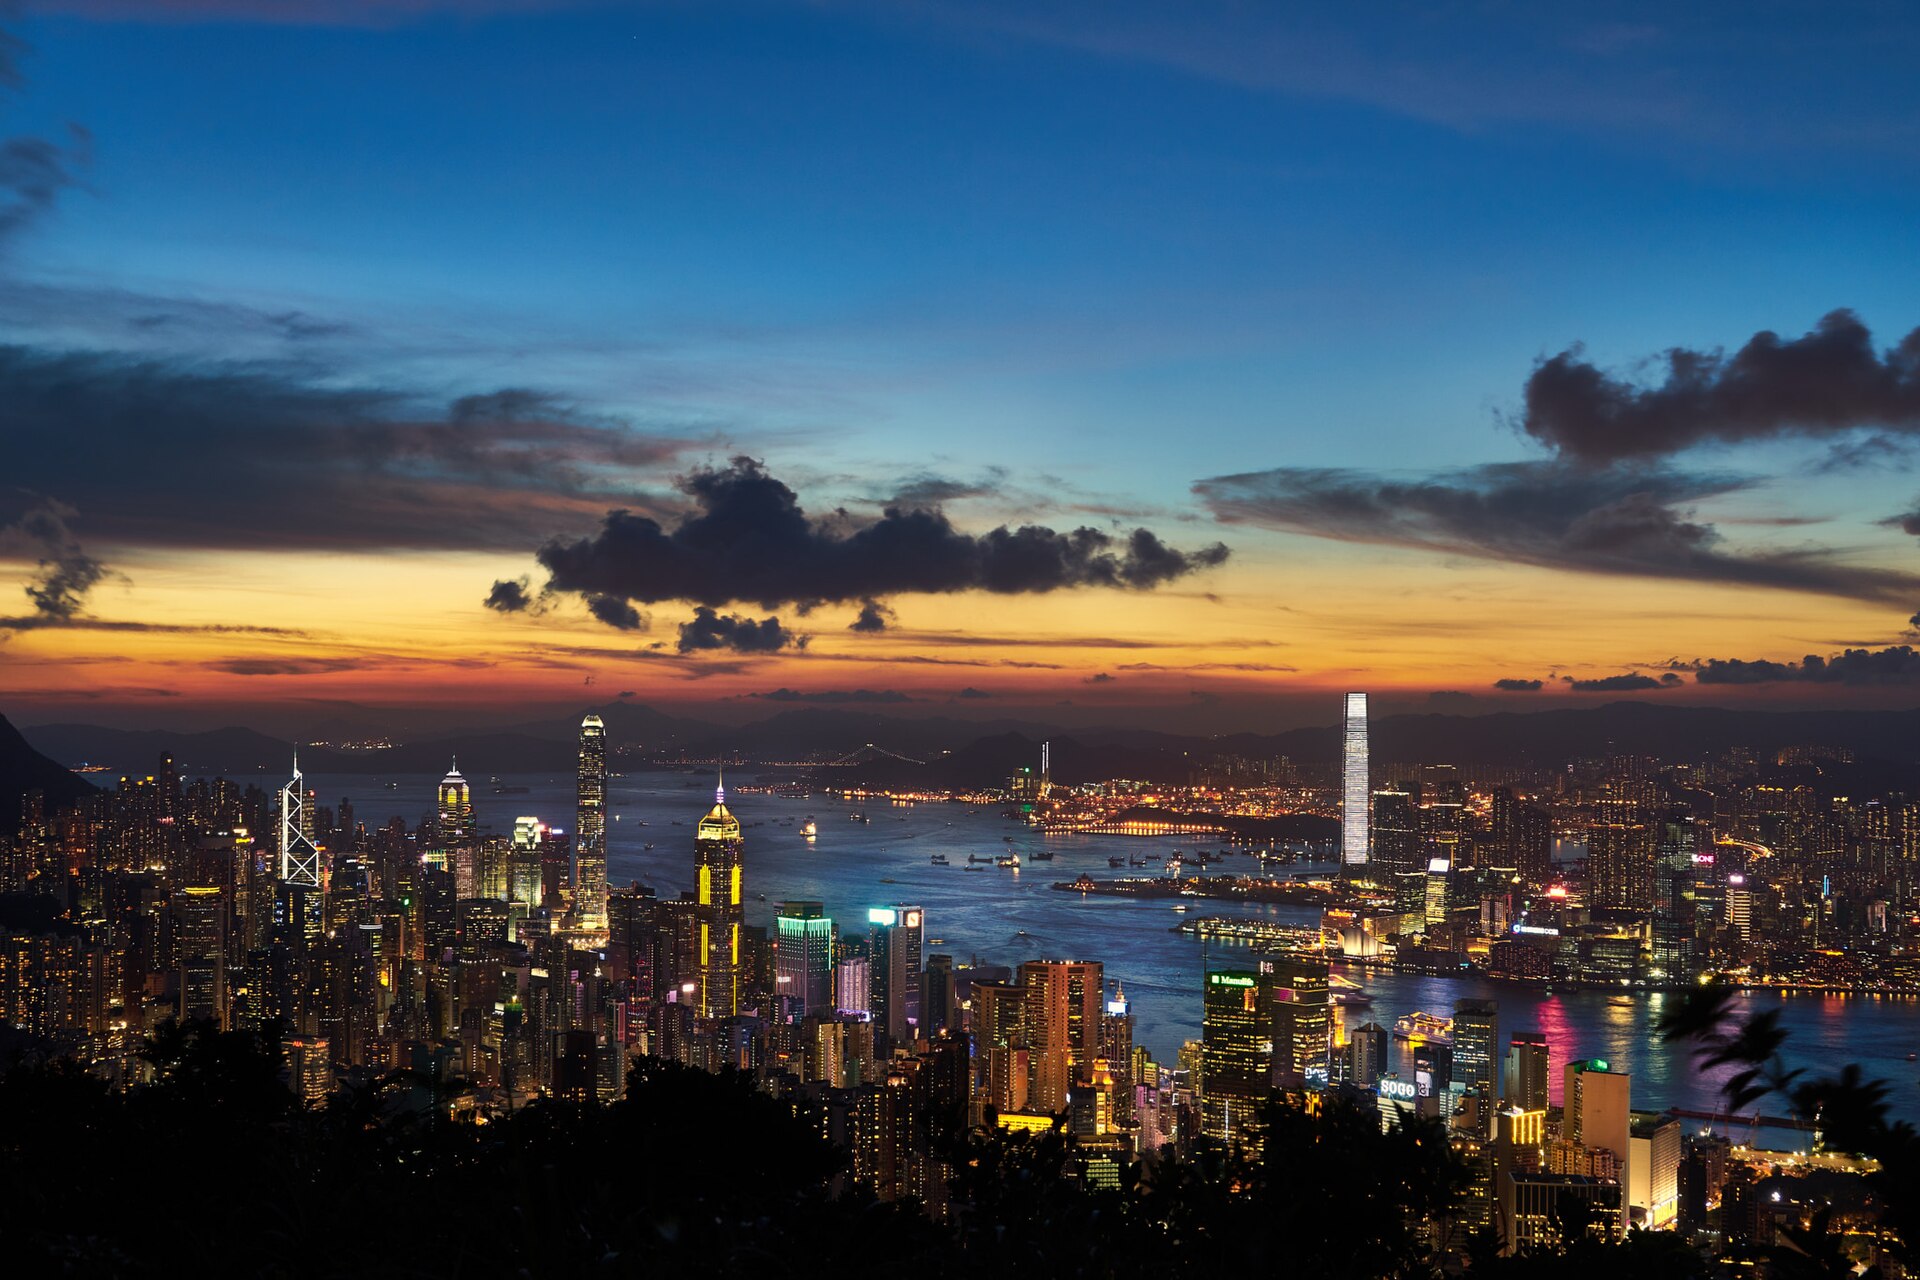
Featured photograph: Mike · image source · CC BY 3.0